


The Wall Street Journal reported this week that retail investors have started wiring AI agents directly into their brokerage accounts. People are writing trading rules in plain English, connecting agents to Robinhood and Webull, and letting software handle rebalancing that used to require a phone call. The Journal is appropriately careful about the risks. Millions of retail agents reacting to the same signal at the same moment could reproduce the 2007 quant meltdown at consumer scale, and nobody really knows what that correlation looks like in a live drawdown.
Those risks deserve to be taken seriously. So does the industry response, which arrived quickly and sounded rehearsed: allocation decisions require human judgment, a licensed professional owes you a duty that no model can owe, and handing your retirement to an algorithm is reckless.
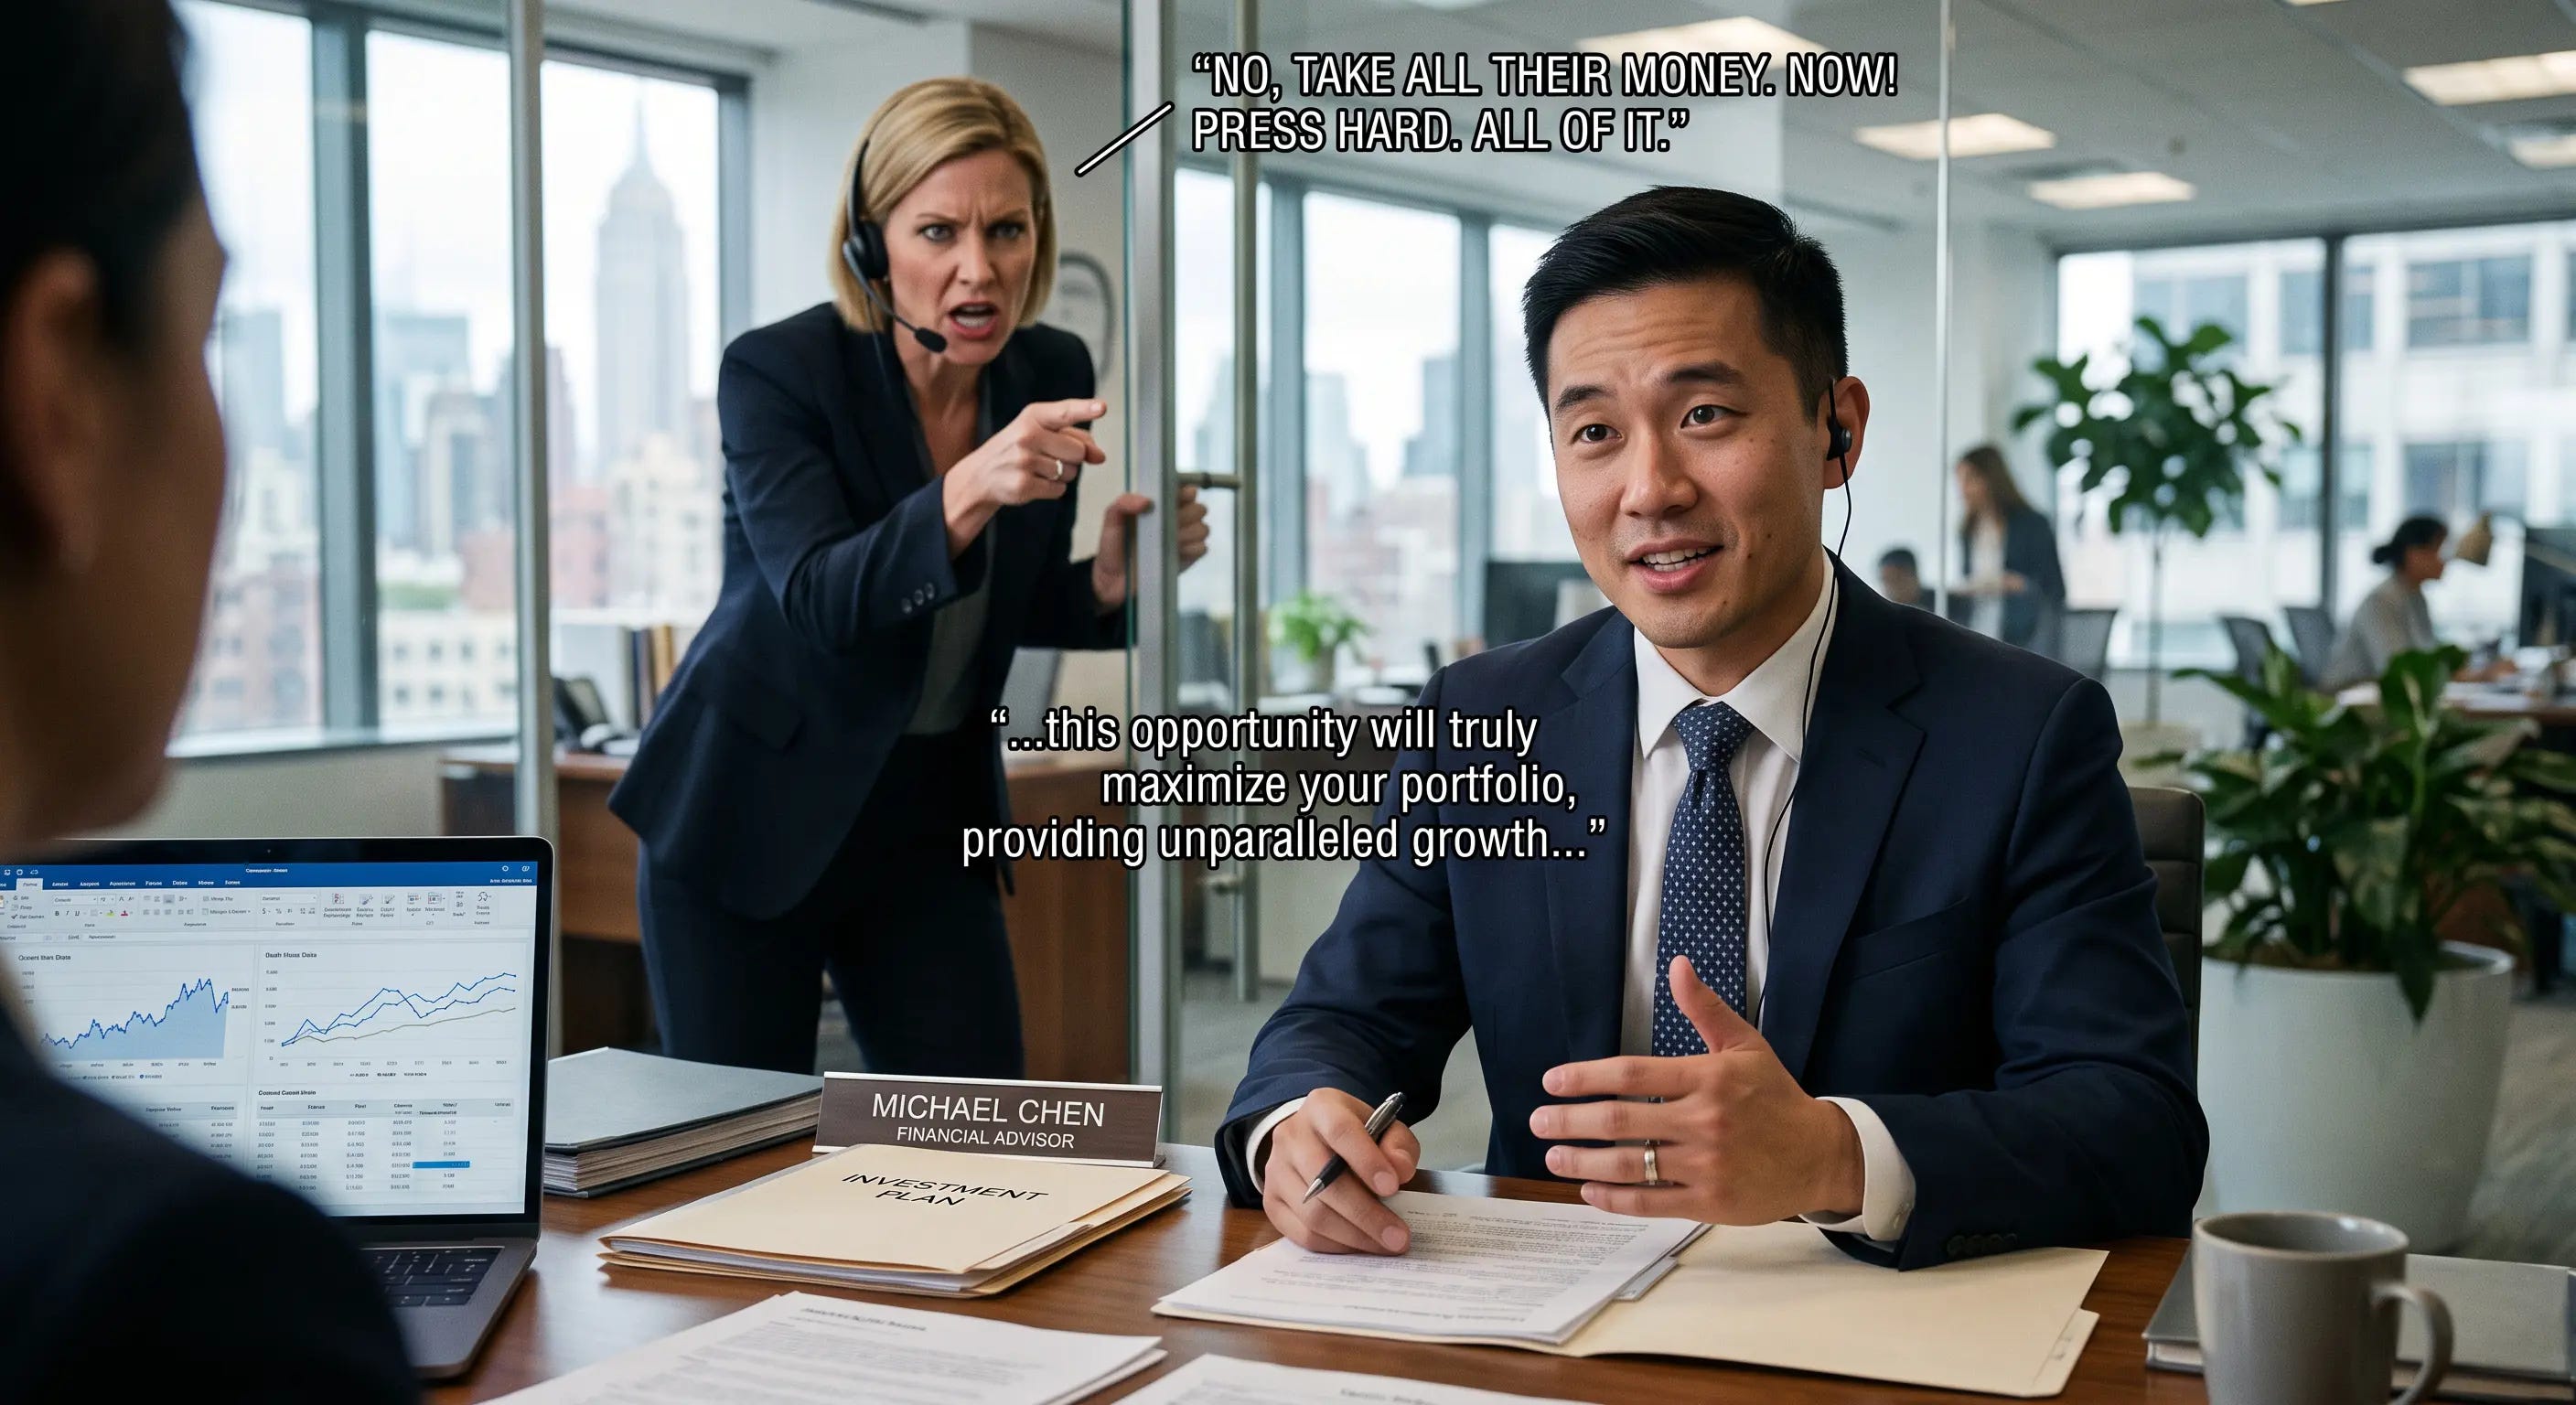
That last argument has a forty-five year audit trail sitting behind it, and the audit trail is public.
The receipts
Start in 1983, with a company that used to make pianos. Baldwin-United had moved into insurance, and its subsidiaries issued single-premium deferred annuities to roughly 165,000 people, a large share of them elderly, most of them told they were buying something safe that paid as much as 15%. More than $3 billion of the things were sold. About three-quarters of that volume moved through brokerage houses: Merrill Lynch, Shearson/American Express, E.F. Hutton, Smith Barney, Kidder Peabody, Prudential-Bache, Paine Webber. In September 1983 Baldwin-United went into Chapter 11 with assets the bankruptcy court would later describe as charitably valued at $9 billion against debts of at least that size, and the annuities froze along with everything else. The brokerages settled the resulting class actions for about $140 million in 1985. Insurance regulators and attorneys general from 37 states ran a separate coordinated recovery. Ohio’s insurance department, which had spent $400,000 investigating, said its findings showed customers had been misled about the returns.
Two years later E.F. Hutton pleaded guilty to 2,000 counts of mail and wire fraud for systematically overdrafting its bank accounts, with daily overdrafts that sometimes ran past $250 million, to generate interest-free float. The firm paid a $2 million fine, $750,000 in investigation costs, and $8 million in restitution. No individual was charged. The most revealing part came the same day, when the SEC granted Hutton a waiver from the rule barring convicted felons from acting as investment advisers, on the stated grounds that enforcing it would disrupt the securities market. A major retail brokerage took a felony conviction at its top operating levels and kept its advisory license, because the regulator judged the alternative worse.
The late eighties brought the cases everyone remembers. Drexel Burnham Lambert pleaded guilty to six felony counts of mail and securities fraud in 1989 and paid $650 million. Salomon Brothers paid $290 million in 1992 over false and unauthorized bids in Treasury auctions.
Prudential-Bache, one of the firms that had distributed the Baldwin annuities, turned up again in October 1993. Through the 1980s it had sold roughly $8 billion of interests in hundreds of limited partnerships, marketed to retail customers as conservative income vehicles roughly comparable to a bank certificate of deposit. They were illiquid, overleveraged, and concentrated in oil and real estate going into the exact wrong decade. The SEC settlement came to $371 million. Five years after that, a federal judge approved a $1.03 billion class-action settlement covering 37 brokerages accused of colluding to keep Nasdaq spreads artificially wide, at the time the largest civil antitrust settlement in the country’s history. The allegation there was price coordination among nearly forty firms, against their own customers.
In April 2003, ten of the largest investment firms in the country signed the Global Analyst Research Settlement: $1.4 billion, split into $487.5 million in penalties, $387.5 million in disgorgement, $432.5 million to fund independent research, and $80 million for investor education. The finding was that research analysts had been issuing favorable coverage to win investment banking business. Testifying to Congress, the SEC chairman quoted an internal Credit Suisse First Boston email in which a technology analyst laid out the unwritten rules for tech research, learned by adapting to whatever the banking group needed in order to keep corporate clients appeased. Citigroup’s Salomon Smith Barney unit paid $400 million. Credit Suisse First Boston and Merrill Lynch paid $200 million each, Morgan Stanley $125 million, Goldman Sachs $110 million, and Bear Stearns, Lehman, J.P. Morgan and UBS Warburg $80 million apiece. There was no meaningful holdout, which tells you roughly how many firms were running a clean version of the business.
The private litigation dwarfed the regulatory number. WorldCom investors recovered $6.13 billion from the underwriting syndicate, the auditors and the directors, the largest securities class action recovery in history at the time. Citigroup paid $2.65 billion of that and J.P. Morgan $2 billion, with Bank of America, Lehman and Credit Suisse First Boston settling alongside them. Enron produced a parallel round: Citigroup $2 billion, J.P. Morgan $2.2 billion, then CIBC, Lehman, Bank of America and others. More than a dozen banks settled across the two cases. These were class actions rather than regulatory fines, which is a real distinction for the accounting and a much smaller one for the customer.
Five months after the research settlement, the mutual fund scandal broke. Fund companies had been permitting favored hedge funds to market-time and late-trade against their own shareholders. Bank of America settled for $675 million. Prudential Equity Group eventually paid $600 million in 2006 in a combined civil and criminal resolution that included an admission of criminal wrongdoing. Janus, Strong, Putnam, Alliance, MFS, Invesco and Pilgrim Baxter all settled. Ordinary shareholders paid the fees; the timers kept the arbitrage.
Running underneath all of it was a quieter industry-wide investigation into how funds bought their way onto recommendation lists. In November 2003, Morgan Stanley paid $50 million for failing to tell customers it was receiving payments to favor certain funds over others. In March 2004, MFS paid $50 million for using the funds’ own brokerage commissions, which is to say money belonging to the shareholders, to buy shelf space at roughly 100 broker-dealers. In December 2004, Edward Jones paid $75 million over its “Preferred Mutual Fund Families” program. The SEC’s order is worth reading closely. Edward Jones told the public and its clients it was promoting those seven fund families because of their long-term investment objectives and performance, while receiving tens of millions of dollars a year from those same families, and never disclosed that the payments were a material factor in who made the list. Its managing principal was required to step down.
In February 2004 the SEC and NASD settled with 15 brokerage firms over breakpoint discounts, the volume discounts investors are owed automatically on front-end load funds. A joint sweep of 43 broker-dealers had found that in roughly a third of eligible transactions the customer simply did not get the discount, with an average of $364 withheld each time. The fines totaled $21.5 million and were set equal to each firm’s projected overcharges, which is another way of saying the penalty for taking money you were not entitled to was giving it back.
Then came auction rate securities. Firms sold ARS to retail customers as cash equivalents comparable to money market funds. When the auctions failed in February 2008, tens of thousands of people discovered their emergency reserve was a long-dated instrument with no bid. The SEC found that Citigroup and UBS knew the market was deteriorating while they were still describing the paper as safe and highly liquid. Regulatory settlements ultimately produced more than $61 billion in buybacks, the largest investor recovery obtained to that date.
Wells Fargo takes the next decade. $185 million in 2016 for approximately 3.5 million accounts opened without customer authorization by employees chasing sales targets. $3 billion in 2020 to resolve the DOJ and SEC investigations into the same conduct. $3.7 billion in December 2022, including a $1.7 billion civil penalty that remains the largest the CFPB has ever imposed, covering wrongful vehicle repossessions, improper foreclosure denials, and surprise overdraft fees across more than 16 million accounts.
The cleanest case in the entire file is one of the smallest. In March 2019 the SEC settled with 79 investment advisers who had put clients into mutual fund share classes carrying 12b-1 fees when a cheaper share class of the identical fund was available to those same clients. Same fund, same manager, same holdings, higher fee, with the difference routed back to the adviser, an affiliated broker-dealer, or the adviser’s own registered representatives. They returned more than $125 million. That is a fee-sharing arrangement operating under the label of advice, and it took a self-reporting amnesty program to surface it.
The pattern survived the tightening of disclosure rules. Beginning in late 2021 the SEC ran a rolling sweep over off-channel communications, because senior people across the industry were conducting business on personal phones where nothing was preserved: $1.1 billion from sixteen firms in September 2022, $289 million more that August, $81 million in February 2024, $390 million from twenty-six firms in August 2024, $63 million in January 2025. More than a hundred firms in total, and that is the SEC’s share alone.
The most recent chapter is cash sweeps. In January 2025, two Wells Fargo advisory entities and Merrill Lynch paid a combined $60 million over programs that defaulted advisory client cash into affiliated bank deposit accounts paying below-market rates while the firms kept the spread. The private suits are still working through the system, roughly twenty-five of them by Oppenheimer’s count. Oppenheimer settled its own for $70 million in April, disclosing in an SEC filing that the plaintiff had been seeking more than $440 million and that it chose settlement over a jury. The claim deadline for affected customers is September 17 of this year.
The part where they sued to avoid the standard
The industry did not merely violate the fiduciary standard on a recurring basis. It fought, successfully and repeatedly, to avoid being subject to one.
In February 2015 the White House Council of Economic Advisers published its analysis of conflicted retirement advice. Savers receiving it earned returns roughly one percentage point lower each year. Approximately $1.7 trillion of IRA assets sat in products generating those conflicts. The aggregate cost came to about $17 billion annually. A worker who rolled over $100,000 at age 45 would reach 65 with roughly $179,000 instead of $216,000.
The Department of Labor’s first attempt to close that gap, in 2010, was withdrawn under industry and congressional pressure. The 2016 rule was challenged by the Chamber of Commerce, the American Council of Life Insurers, and the National Association of Insurance and Financial Advisors, and the Fifth Circuit vacated it in its entirety in March 2018. The 2024 Retirement Security Rule, deliberately drafted to survive the challenges that killed its predecessor, was stayed by two Texas district courts before its September 2024 effective date. The DOL stopped defending it in 2025. Final judgments vacating it were entered in March of this year, and on April 20, 2026, the Department formally restored the 1975 five-part test.
Four attempts across sixteen years. The rule that currently governs whether the person recommending your IRA rollover owes you a fiduciary duty was written when Gerald Ford was in office.
What was actually being sold
Set the enforcement record aside for a moment and ask a narrower question. Was the underlying service any good?
S&P’s SPIVA scorecard found that 79% of active large-cap U.S. equity funds underperformed the S&P 500 in 2025, the fourth-worst result in the scorecard’s 25-year history. Over twenty years, roughly 92% of domestic equity funds trailed their benchmarks. Past the fifteen-year horizon there is no category at all, across domestic equity, international equity and fixed income, in which a majority of active managers outperformed.
Distribution was the product. Selection was the story that made the distribution sound like a service, and that story has been failing its own audit for a quarter century.
The humans are already using the machine
The you-need-a-professional argument runs into trouble here, because the professionals are already delegating the analysis.
Edward Jones and Morning Consult surveyed advisors nationally in May 2026 and found 82% already using AI tools in their practice, with 69% saying it has been positive for the industry. J.D. Power’s 2026 advisor satisfaction study put active AI use at 73% among employee advisors, up from 44% the prior year. Thirty-eight percent of advisors reported that clients are now comparing their recommendations against what an AI tool tells them.
That reframes the choice on offer. It is not human judgment against machine judgment. It is machine judgment with a distribution layer wrapped around it at 1% of assets under management, against machine judgment without one.
What I know from building these systems
I build production agentic systems, which means I spend most of my working life on the exact question the advisory industry spent forty-five years not answering. When I designed the shopping assistant running on our commerce platform, the first architectural decision was not the model, the retrieval layer, or the tool schema. It was who the agent works for. An agent that surfaces products has an objective function, and that function either optimizes for the buyer or for whoever is paying to be surfaced. You cannot leave that ambiguous and then market the result as neutral. The same tension shows up in a wedding-planning agent I built for a Las Vegas chapel, where every recommendation either serves the couple’s budget or the venue’s margin, and pretending there is no tension is a design failure rather than a business model. In a working agentic system the conflict is a line in a system prompt and a row in a database. Anyone with access can read it. That is a different situation from a conflict that only surfaces in discovery, years later, after the money has already moved.
The machine is not virtuous
None of which makes software honest. Software inherits the incentives of whoever wrote its objective and whoever pays for its inference.
In June 2022 the SEC charged three Charles Schwab investment adviser subsidiaries over Schwab Intelligent Portfolios. They paid $187 million, a $135 million penalty plus disgorgement and interest, all of it returned to clients. The robo-advisor charged no advisory fee at all. It made money by requiring client portfolios to hold between 6% and 29.4% in cash, sweeping that cash to an affiliated bank, lending it out, and capturing the spread. Schwab’s disclosures said the cash allocation followed a disciplined methodology seeking optimal returns. Schwab’s internal analysis said the cash would cause clients to earn less under most market conditions while carrying the same risk. The SEC’s enforcement director summarized it as Schwab claiming the cash level was set by sophisticated economic algorithms when it was actually set by how much money the company wanted to make.
That is the 12b-1 share class case with better interface design. The algorithm did not remove the conflict, it automated it and shipped it behind a clean dashboard.
In March 2024 the SEC brought its first AI-washing enforcement actions, against Delphia and Global Predictions, for $400,000 combined. Delphia had told clients for three years that it applied machine learning to their personal financial data to drive investment decisions. It had collected the data, never used it, and never built the algorithm it advertised. Global Predictions marketed itself as the first regulated AI financial advisor and could not substantiate the claim.
The commission-free app has its own arrangement. Robinhood paid the SEC $65 million in December 2020 for failing to disclose that its single largest revenue source was selling customer orders to high-frequency trading firms. Payment for order flow accounted for 81% of its revenue in the first quarter of 2021. FINRA added roughly $70 million in 2021, then $26 million plus $3.75 million in restitution in March 2025, and the SEC took a further $45 million in January 2025.
The argument that actually holds
So the case for the agent is a narrow one, and it has nothing to do with capability.
When you run the agent yourself, against your own broker connection, with a strategy you specified and a trade log you can read line by line, the conflict question becomes answerable in an afternoon. You can inspect the objective. You can check the execution venue and whether it pays for the flow. You can compare what the strategy said against what the system actually did. Four and a half decades of enforcement history is a record of conflicts that were discoverable only by subpoena, and usually only after the money had already moved. Being able to inspect a conflict is a different problem from having to litigate one.
The corollary carries the same weight. If you rent your agent from your broker, running on their infrastructure, tuned to their objective, routing to their preferred venue, you have rebuilt the precise structure you were trying to leave, with a chat interface bolted to the front. The question to ask of any system managing your money is not how capable the model is. It is who pays for the inference.
What survives
The financial advisor is dying, and not because a model got better at picking stocks. The model removed the one thing the picking story existed to justify, and forty-five years of penalties, disgorgement and forced buybacks had already established that the story was never the business.
What survives is the part that was never about selection. Tax sequencing across account types. Estate structure. Concentrated position management. The twenty-minute conversation that stops someone from liquidating everything in the third week of a drawdown, which no agent has yet shown it can do and which is worth more than any allocation decision most people will make. That work is real and worth paying for directly, in a fee you can see, to someone who does not also get paid by the products they recommend.
The obituary was written in installments, and the industry paid for each one.
Disclosure
I am not a financial advisor, a broker, or a registered investment adviser. Nothing here is investment advice, and nothing here is a recommendation to buy, sell, or hold any security, or to adopt any particular strategy or tool. This is commentary on an industry’s regulatory record and on how agentic systems get built.
Every enforcement action described above is drawn from public sources: SEC, Department of Labor, Department of Justice, FINRA and NASD releases and orders, federal court opinions, state regulator announcements, and the companies’ own filings. In nearly all of these matters the firms settled without admitting or denying the findings, and several of the largest figures cited are private class action recoveries rather than regulatory fines. Past enforcement against a firm or a category of product tells you nothing reliable about future investment returns.
Decisions about your own money, including any decision to hand them to software, are yours. If you want help with them, get it from someone who will put their fiduciary duty to you in writing.
About the Author
Gal Ratner is the founder and CTO of Inverted Software and WhiteStar Labs, and Chief Architect at Prana Entertainment, a Las Vegas enterprise software and AI consultancy. He has spent nearly thirty years shipping production systems on the Microsoft and .NET stack for clients including Microsoft, Sony, Rockstar Games, 2K Games, Best Buy, and Allegiant Air, and was a Los Angeles Business Journal CTO of the Year finalist. His current work is production agentic AI: MCP servers, the Microsoft Agent Framework, RAG pipelines, SQL Server 2025 vector search, and the PLogger observability framework. He builds and operates agentic systems handling live commerce and scheduling workloads, and writes about the gap between what executives say about AI and what practitioners actually ship. He is the author of the novel The Archive of Lost Suns. He publishes at galratner.substack.com.