


It went up the ladder, into share buybacks, and into a handful of AI labs that already won. Here is how the exits got welded shut, why the door was never open for you in the first place, and the two specific levers that could pry it back open if anyone with power wanted to.
Read these two sentences back to back and tell me they describe the same economy. In 2024, the average chief executive at an S&P 500 company took home $18.9 million, a seven percent raise, while the typical American worker made $49,500 and got a three percent bump. In the first five months of 2026, more than 113,000 tech workers were shown the door across roughly 179 companies, an average of about 825 people a day since New Year’s, and the trackers expect the year to close near 370,000.
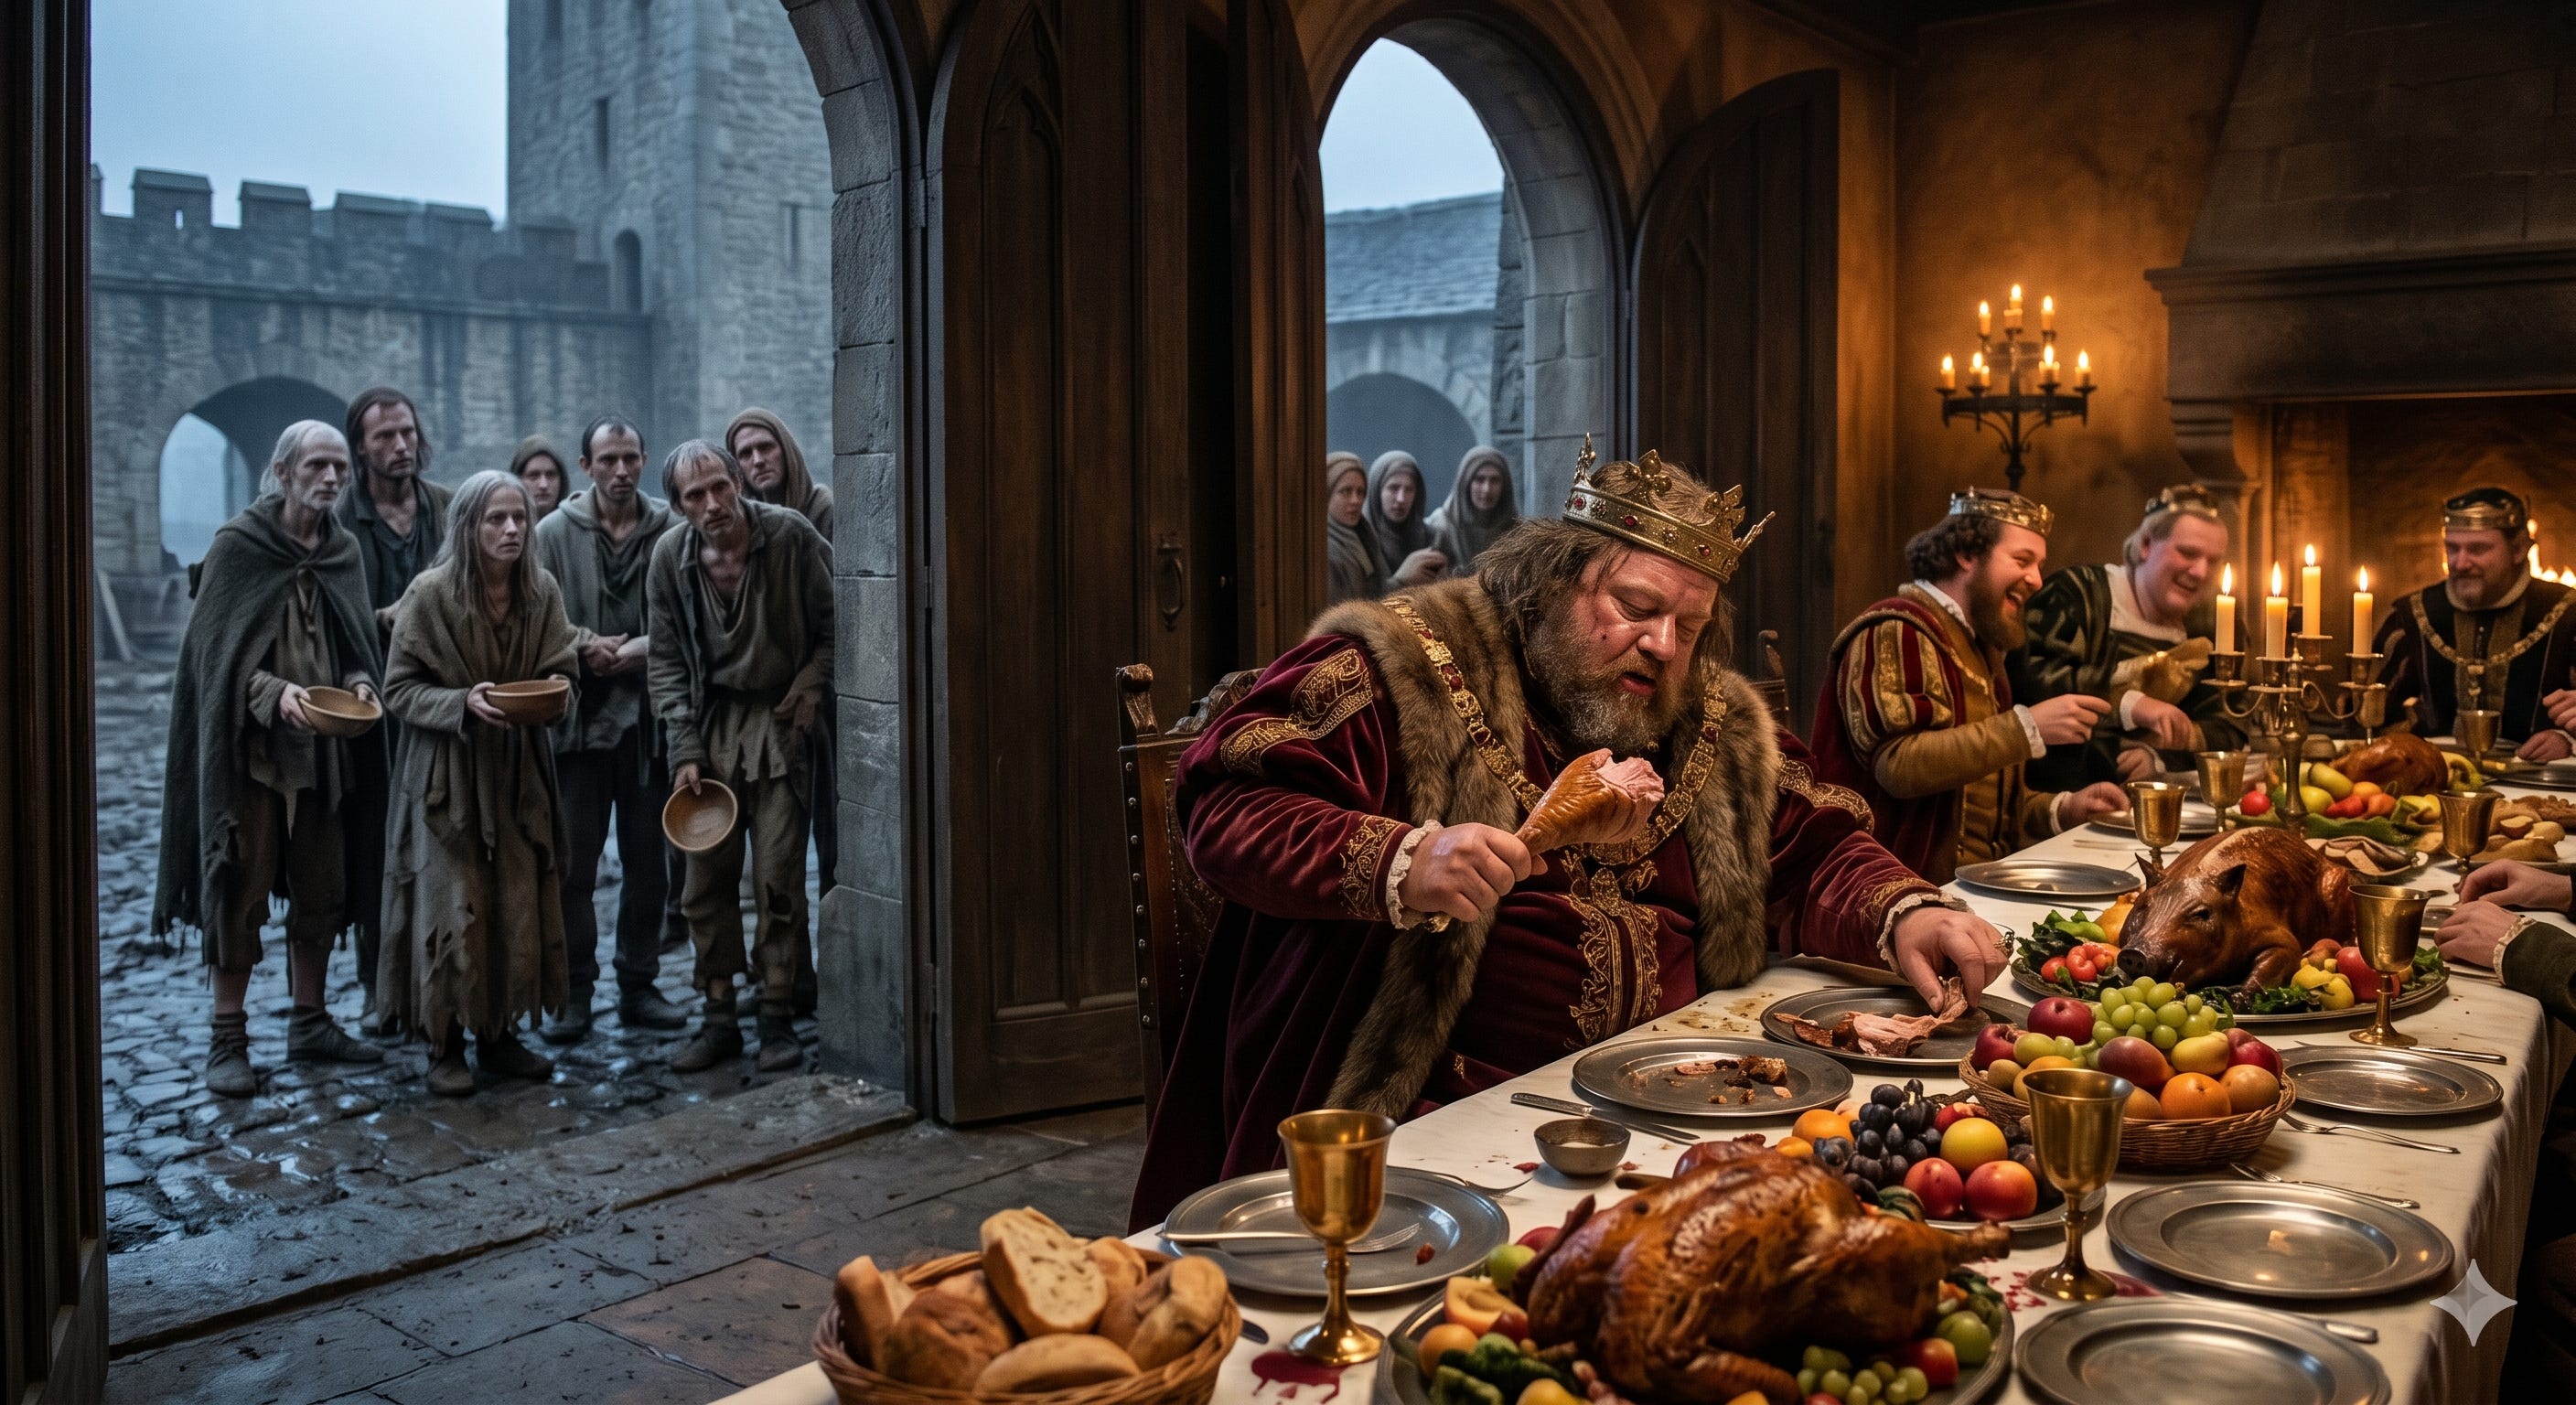
Those are not two economies. They are one machine, and it is working exactly as designed. The story we keep getting told is that this is capitalism doing its brutal but ultimately fair thing, sorting the efficient from the wasteful, rewarding risk, punishing complacency. That story is a lie, and not a small one. What we are living through is not a market. It is a toll booth, owned by people who got there first, who pulled the ladder up behind them, and who now charge rent on every road you might use to catch up. The little guy cannot compete because the game is no longer about competing. It is about who already controls the choke points.
The 285-to-1 Year
Start with the number that should end every debate about whether the deck is stacked. The AFL-CIO’s 2025 Executive Paywatch report, built from proxy statements filed with the SEC for more than 3,800 corporations, found the average CEO-to-worker pay ratio at S&P 500 companies hit 285 to 1 in 2024, up from 268 to 1 the year before. The median employee at one of these companies, the report calculated, would have had to start working in the year 1740, before the United States existed, to earn what the average CEO collected in a single year.
At Starbucks, the gap was 6,666 to 1. Brian Niccol, brought in to run the company in the fall of 2024, pulled down an annualized $97.8 million while the typical Starbucks worker made under $15,000. To match one year of Niccol’s pay, that median barista would have needed to start pulling shots during the Stone Age. And then there is Elon Musk, whose Tesla board has proposed a pay package that could be worth up to a trillion dollars over a decade, a figure the AFL-CIO notes is more than the combined annual pay of every other S&P 500 CEO multiplied by a hundred, and seventeen million times what the median Tesla worker makes.
I want to be precise here, because the defenders of this arrangement always reach for the same dodge: most of that compensation is stock, not cash, and it only pays out if performance targets are hit. True. It is also beside the point. The mechanism by which that stock becomes worth a fortune is the same mechanism that put your coworkers in the unemployment line. The executive class is paid in the appreciation of the share price, and the fastest, most reliable way to goose a share price in 2026 is to announce that you are firing people. The incentive is not hidden. It is the whole point.
The Jobless Boom
Chen Zhao, chief global strategist at Alpine Macro, has a name for what is happening: a jobless boom. Corporate profits are at records. GDP is expanding. The stock market keeps climbing. And the white-collar labor market is quietly collapsing in on itself. This is not a recession. Recessions are when companies cut because they are bleeding. This is companies cutting because cutting pays.
Look at who did the cutting in 2026 and why. Amazon eliminated 16,000 corporate jobs in January, on top of 14,000 announced the previous fall, one of the largest reductions in its history. Meta moved to cut around 8,000 people in May while signaling it might redirect headcount toward AI roles, after slicing 1,500 from Reality Labs in January. Cisco cut nearly 4,000. Intuit cut 3,000, seventeen percent of its global workforce, while insisting it was “not about AI.” PayPal announced plans to remove nearly 4,800, around twenty percent of its people, with the CEO telling investors the goal was to strip out “duplication and layers” and accelerate automation. Jack Dorsey’s Block cut its headcount nearly in half. By the Nikkei Asia analysis, close to forty-eight percent of the layoffs tracked through April were explicitly attributed to AI and workflow automation.
Now hold that next to where the money actually went. In 2025, S&P 500 companies spent over a trillion dollars buying back their own stock, a record, with the twelve-month total through September reaching $1.02 trillion, up eleven percent from the prior year. Add dividends and total shareholder payouts hit roughly $1.685 trillion in that same stretch. The top twenty companies accounted for about half of all the buybacks. A buyback does one thing mechanically: it shrinks the number of shares outstanding, which lifts earnings per share, which lifts the stock, which lifts the value of the executive equity packages we were just talking about. Firing workers funds the repurchases. The repurchases lift the stock. The stock fattens the executives. The loop closes, and it closes around your salary.
This is why the market cheers the firings. When Meta’s cuts leaked, the stock jumped. When Oracle let go of tens of thousands, the stock jumped. When Block announced it was cutting forty percent of its people, the stock jumped more than twenty percent. The signal to every CEO in America could not be clearer. You are punished for hiring and rewarded for firing. Meanwhile the same four companies doing much of the cutting, Meta, Amazon, Microsoft, and Alphabet, committed roughly $725 billion in capital spending in 2026, up about seventy-five percent year over year, nearly all of it earmarked for AI data centers, chips, and the infrastructure to run them. They are firing humans and buying GPUs with the savings. That is the blunt version, and nobody at the top is even bothering to deny it anymore.
The Contract That Only One Side Still Honors
There is a legal instrument that makes all of this frictionless, and almost nobody talks about it because we signed it without reading it. Every one of us, on the first day of nearly every job in America, agreed to at-will employment. In forty-nine of fifty states, Montana being the lone exception, it is the default. It means either side can end the relationship at any moment, for any reason or for no reason at all, with no cause required and nothing owed. When you took the job, you waived the right to keep it.
Here is the thing worth understanding: at-will was not designed as a weapon. It was designed as a symmetry. The deal was supposed to cut both ways. The company owes you no obligation to keep you, but you owe the company no obligation to stay. You can walk out the door for a better offer the same afternoon they can walk you out of it. That balance only works, though, under one unstated condition: that both parties act in good faith. It worked when a layoff actually meant something had gone wrong, when the company genuinely could not afford you, when letting you go was a last resort rather than a quarterly tactic. Under those conditions, at-will was a fair bargain between two parties who each carried real risk.
That good faith is gone, and the numbers prove it. The companies doing the firing in 2026 are not in trouble. Oracle posted a ninety-five percent jump in net income to $6.13 billion and still sent dawn emails terminating tens of thousands. Cisco announced four thousand cuts on top of record revenue, and its stock rose twenty percent on the news. These are not distress signals. The layoff has been quietly repriced from an admission of failure into a margin-optimization tool, and at-will is the legal mechanism that lets a profitable company discard a performing employee with no cause, no warning, and no obligation, purely because a spreadsheet says the share price will tick up. One side of the contract kept its end of the bargain. The worker showed up, performed, turned down other offers, absorbed the institutional knowledge that lives in no document. The other side pocketed all of that and then invoked a clause written for emergencies to harvest it for the quarter. The contract assumed mutual good faith. Only one party is still honoring it.
So here is the amendment I would write. Not the abolition of at-will, because at-will still makes sense for genuine cause, for misconduct, for an employee who truly cannot do the job, and for a company that is actually failing and must shrink to survive. Keep all of that. The amendment is narrow and it is this: a performance protection. An employee with a documented record of meeting or exceeding their stated performance standards may not be terminated, at a profitable company, solely as part of a headcount reduction undertaken to cut costs or lift the share price. If a profitable firm wants to eliminate a performing worker’s position, the burden shifts to the employer to demonstrate that the role is genuinely redundant, not merely that removing the human improves the margin. Pair it with notice and severance that scale with tenure, and with a clawback on the executive equity gains realized in the window around a mass layoff at a profitable company, so that the people who profit from the cut have skin in proving it was necessary.
The objection writes itself: this kills hiring flexibility, it makes companies afraid to staff up, it puts a lawyer between every manager and every termination. It does none of those things, because of how narrowly it is drawn. It binds only profitable companies, only when they are firing demonstrably performing people, only when the reason is cost or stock price rather than cause or genuine necessity. A struggling company can still restructure. A poor performer can still be shown the door. A startup can still hire and fire as it finds its footing. All the amendment does is restore the one condition the doctrine always quietly depended on and recently lost: that you cannot use a clause written for mutual good faith to act in obvious bad faith. It puts the good faith back in writing, because the honor system stopped working the moment the firings started paying better than the products.
Where All the Money Went
Here is the part that matters most if you are the little guy, the founder, the person who actually wants to build something. The capital that used to be available to fund a thousand different bets is now flowing into one. According to PitchBook, AI startups captured $192.7 billion of the $366.8 billion in global venture capital deployed in 2025, the first time in history that a single sector took the majority of all venture dollars. In the United States the concentration ran even higher, with AI pulling in sixty-four percent of venture investment in the first half of the year and, by the third quarter, nearly sixty-three percent of all U.S. venture capital.
To understand how abnormal that is, measure it against the manias we already lived through. At the peak of the dot-com boom, internet startups took about thirty-nine percent of venture funding. In the mobile revolution, app companies reached thirty-one percent. Crypto’s frenzy in 2021 topped out around twenty-two percent. AI’s share dwarfs every one of them. And inside that share, the money is not spread around. It is hoarded at the very top. In the second quarter of 2025, more than a third of all U.S. venture dollars went to just five companies. OpenAI raised roughly $40 billion led by SoftBank. Anthropic raised $13 billion led by ICONIQ. Musk’s xAI raised $10 billion. By Crunchbase’s count, U.S.-based AI companies alone captured $159 billion, seventy-nine percent of every AI venture dollar on earth.
Now watch what that does to everyone outside the blessed circle. The total number of venture funds is collapsing even as the dollar figures balloon. PitchBook data show only about 823 venture funds raised roughly $80 billion in 2025, a brutal drop from 2022, when 4,430 funds raised around $412 billion. Fewer funds, bigger checks, all aimed at a handful of names that already won. If you are building anything that is not a frontier AI lab, the institutional money that used to fund the boring, useful, profitable middle of the economy has been vacuumed up and pointed somewhere else. Analysts at firms like SoftwareSeni have already drawn the obvious historical parallel: the companies that needed capital during the mobile-app concentration of 2011 and could not raise it simply did not survive to see the recovery. Capital concentration is not a neutral preference. It is a death sentence handed to everyone it skips.
And the second-order effects compound. Technical talent follows the funding. Research follows the funding. When more than half the venture capital in the country tilts toward a single paradigm, the entire ecosystem tilts with it, and the engineer who might have built a tool you actually needed instead goes to build the thing that is currently on fire with money. The market did not choose this through some wise invisible hand. A small number of people decided where the capital goes, and they decided it goes to each other.
Even the Computers Got Expensive
If you want a physical, tangible sign that this is not a normal market, look at the machine on your desk. The AI buildout is so vast that it has broken the supply chain for the most basic component in computing: memory. Counterpoint Research found that DRAM prices rose eighty to ninety percent quarter over quarter between December 2025 and February 2026, the steepest increase since the memory boom of 2017 and 2018. A 32GB DDR5 desktop kit that ran $220 to $280 in late 2025 was selling for $420 to $510 by February. Framework, the modular-laptop maker, told its customers plainly that it would now charge close to ten dollars per gigabyte, “as close as possible” to its own supplier costs, and warned it would likely have to raise prices again within a month.
The cause is not mysterious and it is not consumer demand. The memory manufacturers can earn far more selling high-bandwidth memory and server-grade DDR5 to the AI data-center buildout than selling commodity RAM to people who want to upgrade a laptop, so they have reallocated their wafer capacity toward the highest bidder. The hyperscalers are not just buying chips. They are buying the entire memory ecosystem around the chips, and everyone else is left fighting over the scraps at a premium. Industry analysts expect this to bleed into smartphones and PCs and to persist well into 2027. The richest companies in the world are quite literally making it more expensive for you to own a computer, because they need the parts more than you do and they can outspend you forever.
Think about what that means for the founder working out of a spare bedroom. The cost of the AI gold rush is being socialized onto everybody who has to buy hardware, while the upside is privatized into the balance sheets of four companies. The tools you would use to compete are getting more expensive precisely because the incumbents are competing so hard with each other that they have bid up the price of the raw materials. You are paying a tax to subsidize the very concentration that is squeezing you out.
This Is Not a Free Market. It Is a Gated One.
Put it all together and the word for this is not capitalism. Capitalism, the version in the textbook, is supposed to be the system where a better mousetrap and a willingness to work beats incumbency. What we have instead is a system of gatekeepers, and the gates have been closing for decades. The Institute for Local Self-Reliance has documented that the number of new ventures launched in America each year has fallen by nearly two-thirds since 1980. Ryan Decker, an economist at the Federal Reserve, found that startup rates have been declining for decades and that the decline accelerated after 2000, concluding that the incentives for entrepreneurs to start new firms have steadily eroded.
The carnage is concrete. Between 1997 and 2012, the country lost more than 70,000 small manufacturers and 108,000 local retailers, and the number of community banks and credit unions, the institutions that actually used to lend to small business, was cut in half, from about 26,000 to 13,000. The reason is not that Americans suddenly got lazy or lost their nerve. It is that the rules changed. Antitrust enforcement was hollowed out under the so-called consumer-welfare standard, which redefined the goal of competition policy from keeping markets open to merely keeping prices low, and in doing so quietly legalized the predatory pricing, the tying, and the loss-leading that dominant firms use to crush new entrants before they can scale. When a monopolist learns of a new competitor, it can sell below cost until that competitor bleeds out, and for the last thirty-five years that has been, effectively, allowed.
You can watch it happen in plain sight. A small business that wants to reach customers online is funneled onto Amazon’s marketplace, where Amazon then takes up to fifty cents of every dollar that small seller earns, through fees and required logistics and advertising. That is not a competitor competing. That is a landlord collecting rent on the only road into town. The pattern repeats across food, pharmacy, banking, telecom: a handful of firms control the inputs, the distribution, and the shelf space, and the independent operator is left to negotiate with the people who own the entire field they are standing on.
This is the trap, and it is worth saying out loud because the system depends on you not naming it. To succeed, the conventional wisdom now goes, you need connections, you need capital you cannot raise, and you need the right resume from the right school to be taken seriously by the people who control the money. None of those are skills. They are access. And access is exactly what a gated system rations. The genius with a better idea and no network is not beaten by a better idea. He is beaten by the gate.
Tax the Ratio, Not the Worker
If you want to break the loop, you do not lecture executives about morality. You change what the tax code rewards, because the tax code is the one set of rules they actually respect. Right now the code is neutral-to-friendly on shedding people. Cut payroll, watch margins rise, watch the stock rise, fund the buyback, collect the equity. Nowhere in that chain does firing a worker cost the company anything. So make it cost something, and key the cost to the exact behavior we want to discourage.
Here is the lever I keep coming back to: a tax keyed to revenue per employee. Take a company’s revenue, divide it by its full-time-equivalent headcount, and you get a single number that captures, better than any other, the thing this entire essay has been describing, which is the generation of enormous revenue off a tiny, heavily leveraged, increasingly automated workforce. Then you tax that ratio, progressively. Below a floor, say a few hundred thousand dollars of revenue per employee, you owe little or nothing. Above it, the rate climbs, and at the very top it climbs steeply.
Look at how far apart the real numbers already sit, because the spread is the whole argument. As of late 2025, NVIDIA was running about $4.4 million in revenue per employee. Netflix, about $4.15 million. Apple, around $2.4 million. Meta, $2.2 million. Alphabet, roughly $1.9 million. A real-estate firm like VICI Properties generates about $142 million per head off a staff of twenty-seven people. Now set that against the part of the economy we claim to care about. A labor-intensive small business, a restaurant, a regional services firm, a workshop, typically runs somewhere between $100,000 and $200,000 of revenue per employee, because it actually has to hire human beings to do the work. Under a revenue-per-employee tax, that small employer pays almost nothing. The lean giant generating two million per head pays real money on every dollar above the line.
And here is the part that makes it bite, the part that inverts the incentive at the center of this whole machine. A layoff mechanically raises your revenue per employee. Same revenue, fewer heads, higher ratio, higher tax. For the first time, firing a performing worker would show up as a cost on the very next return, instead of as a reward on the next earnings call. The CEO who today gets a twenty percent stock pop for cutting four thousand people would, under this rule, also get a tax bill that grows with every name on the list. You would not have to argue with him about whether it is decent. The spreadsheet would argue for you.
Notice what the ratio does that a simple tax on bigness never could: it keys to labor intensity, not size. It does not punish a company for being large. It punishes a company for generating a fortune while employing almost no one. Amazon, for all that I have said about it, runs only about $410,000 in revenue per employee, because it genuinely staffs 1.6 million people to move the boxes. Under this rule the tax would land lighter on Amazon than on a company a fraction its size that automated its workforce out of existence. That is not a bug. That is the entire design. The point is to reward the employer of people and to make the displacement of people expensive in proportion to how lucrative that displacement is.
The objections are predictable and they are answerable. Companies will reclassify employees as contractors to shrink the headcount denominator, so you count full-time equivalents including the dependent contractors that labor law already strains to capture. The tax punishes productivity, the critics will say, but it does not, because it is not aimed at productivity; it is aimed at the concentration of revenue into fewer and fewer hands, which is the externality the rest of us are paying for in lost jobs and dead startups. Revenue is not profit, someone will note, and that is precisely why I use revenue and not profit, because profit is the number corporations have spent a century learning to make disappear, while revenue per head is the lean-and-mean metric their own executives already brag about on stage. You cannot hide from the number you put on the slide. Use the proceeds to cut the burden on small employers and to fund the transition for the workers the giants discard. Tax the ratio, and you stop taxing the worker.
Naming the Machine
None of what I just described is utopian, and that is the point worth sitting with. A performance protection inside at-will and a tax keyed to revenue per employee are not revolutions. They are plumbing. They are mechanical adjustments to incentives that already exist, written in the same dry language as the rules that currently reward the firing. The reason they are not law is not that they would fail to work. It is that the people who benefit from the present arrangement are the same people who write the rules, fund the campaigns, and own the platforms where the argument would have to be had. The gate keeps itself.
So no, you are not imagining it, and you are not failing because you are not good enough. The numbers are not ambiguous. Executive pay at a record while the firings mount. A trillion dollars spent buying back stock instead of paying or keeping workers. Half the nation’s venture capital funneled into one sector and most of that into five companies. The price of a computer rising because the giants need the parts more than you do. New business formation down by two-thirds in a generation. A labor contract that one side stopped honoring the moment dishonor became profitable. These are not the symptoms of a vibrant free market. They are the signature of a small group of people who reached the top, sealed the entrances, and rebranded the rent they collect as the natural order of things.
I am not going to insult you with some tidy uplift about hustle and resilience, because resilience is what they sell you so you will keep paying the toll without complaint. But I will say this. The first thing they take from you is not your money. It is your ability to see the machine clearly, to mistake a rigged game for your own inadequacy. Refusing that confusion is the one move they cannot price, fund away, or buy back. Name the toll booth for what it is. Name the fixes that exist and are kept off the table on purpose. Stop apologizing for not having the connections, the pedigree, the access that was never on offer. The anger you feel reading the 285-to-1 number is not bitterness. It is accuracy. Hold onto it. It is the only thing in this entire economy that they have not yet figured out how to take a cut of.
I honestly wonder how long they can keep doing this before their scheme turns on itself? It seems that inflating stock values by ginning up investors with these sort of trendy layoff announcements can only work so many times... I can't see it working forever, or am I being naive?